Cash advance loans in the UK: alternatives and repayment options
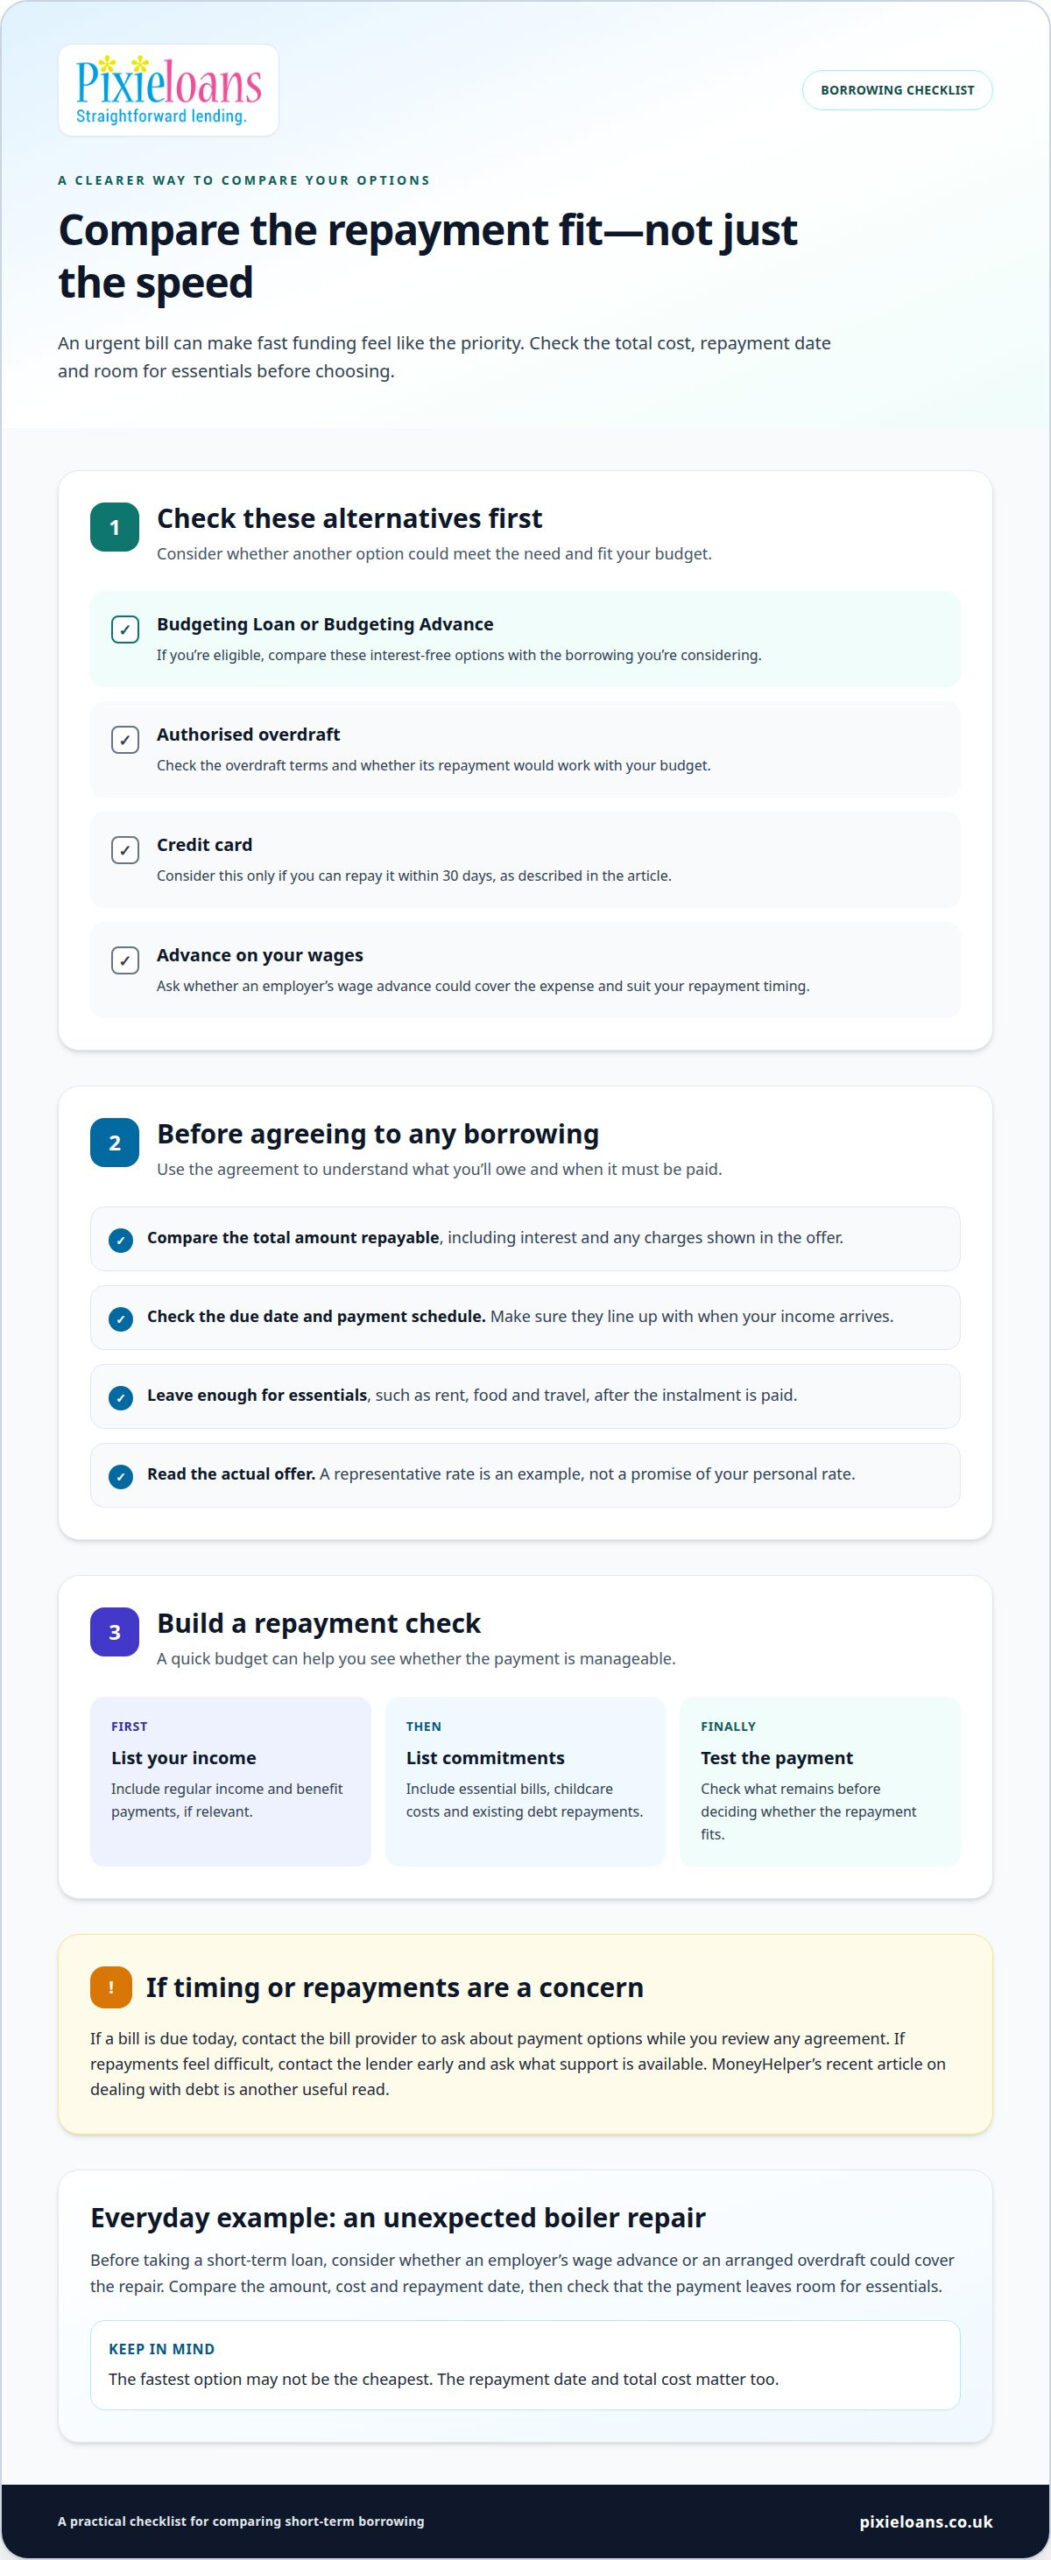
The fastest borrowing option may not be the cheapest. If you’re weighing up cash advance loans in the UK, compare them with an interest-free Budgeting Loan or Budgeting Advance if you’re eligible, an authorised overdraft, a credit card you can repay within 30 days, or an advance on your wages.
It’s understandable to focus on getting an urgent bill paid, but the repayment date and total cost matter just as much. For example, if your boiler needs an unexpected repair, consider whether an employer’s wage advance or an arranged overdraft could fit your budget before taking on a short-term loan. MoneyHelper’s recent article on dealing with debt is another useful read if repayments feel difficult.
This article explains how to compare payday loan alternatives, what soft and hard credit checks may involve, and how early repayment and support with financial difficulty work. You’ll also find practical ways to assess affordability, plan repayments and decide which next step best suits your circumstances.
Key Takeaways
- Compare borrowing options by their total cost and repayment fit; eligible benefit claimants may be able to access an interest-free Budgeting Loan or Budgeting Advance.
- Learn how soft and hard credit checks differ, and what each may mean when you apply.
- Find out what to consider before repaying a loan early, including how it could affect your remaining balance.
- Build a repayment plan around your regular budget, and explore support options early if keeping up becomes difficult.
Alternatives to Payday Loans: Which One to Choose?
Compare the amount, interest and repayment date before choosing short-term borrowing. When weighing up cash advance loans in the UK, consider whether an authorised overdraft or wage advance could meet the need instead.
Loan amounts and customer eligibility
Applicants generally need to be at least 18, live in the UK, have regular income and hold a UK bank account. A lender assesses your application and credit history before deciding whether to offer a loan and what amount may be affordable. New and returning customers should compare the actual offer, rather than assume previous borrowing means a larger amount. Check the interest and total repayment shown in the agreement. Pixie Loans’ short-term loan information explains this type of borrowing.
Funding speed after signing
After you sign the loan agreement, the lender processes the payment. When funds reach your account depends on the lender’s processing and your bank’s payment handling. Signing isn’t a reliable way to know the exact arrival time. If a bill is due today, contact the bill provider about payment options while reviewing the agreement. A direct lender provides the loan itself; an intermediary connects applicants with lenders. Understand which role applies before accepting an offer.
Same-day loan terms
A same-day loan describes expected funding timing, not a separate amount or repayment structure. Before signing, identify the due date, interest and total amount repayable. Check that the instalment leaves enough for essentials, such as rent, food and travel. If the payment date clashes with payday, compare alternatives first.
This shows why the amount borrowed is only part of comparing cash advance loans in the UK. An authorised overdraft, an employer’s wage advance or a credit card repaid within 30 days may be alternatives. Eligible benefit claimants may also compare an interest-free Budgeting Loan or Budgeting Advance. Compare each option’s terms with your budget before deciding.
Soft and hard credit checks
A soft credit check gives a lender an initial view of your credit file. It doesn’t affect your credit score, and other lenders can’t see it as an application search. A hard check usually follows a formal application and leaves a record on your file. Several applications in a short period can concern future lenders, so compare options before applying.
During an application, a lender considers more than your credit score. It can review your credit history, income, regular outgoings and existing borrowing to assess affordability. Missed payments or other credit commitments can affect its decision, but your current situation matters too. Before applying, list your essential bills and debt repayments, then work out what you could afford without missing another payment.
The Financial Conduct Authority has regulated payday loan lenders since 2014. High-cost short-term credit is designed for short borrowing periods, so look closely at interest, fees and the total repayment. A representative rate is an example used to describe a credit offer, not a personal promise. Read the actual terms offered to you and compare the repayment date with your income schedule.
Receiving benefits doesn’t automatically prevent an application. Some lenders consider benefit income as part of affordability, alongside other income and regular commitments. Eligibility depends on the lender’s assessment, so give accurate details about your income and spending. For example, include a regular benefit payment and any rent or childcare costs when working out your monthly budget.
Before submitting an application, check whether the initial eligibility stage uses a soft search or a hard search. Then review the amount, interest and repayment schedule in the offer. If you decide to proceed, the application form is the next step for providing your details.
Can I pay off my loan early?
Early repayment may reduce interest, but the effect depends on the loan agreement. Check the settlement figure and any charges before changing your payment plan.
Early repayment flexibility
UK personal loans can be repaid early without penalty. For other borrowing, read the agreement to see how early payment affects interest and the remaining balance. Ask for a settlement figure before paying, then compare it with your scheduled payments. For example, if a work bonus arrives, set aside essential bills first and use only the amount you can afford towards repayment.
A representative APR helps describe the cost of a credit product, but it isn’t necessarily your personal rate. Use the repayment example in the agreement to understand the total amount due and each payment. If the example differs from your offer, base your budget on your own agreement. Check the interest, payment dates and final balance before accepting.
Settlement fees and repayment charges
Early repayment and settlement charges depend on the agreement and type of borrowing. Check the terms for any charge before making an extra payment, and ask how the lender applies it. A clear settlement figure should show what you need to pay to close the loan. Keep the confirmation and payment record after settling.
Late payments can lead to charges or other consequences set out in the agreement. If your pay date changes or a bill leaves you short, contact the lender before a payment is missed. Explain the change in your situation and ask what repayment support is available. Don’t take further lending simply to cover a payment without assessing the effect on your budget.
If repayments are becoming difficult, list essential spending, income and debts before seeking debt advice. This gives an adviser a practical view of your finances and helps you discuss possible next steps. Review your budget after any change, such as a new work schedule, and keep an agreed repayment plan accessible. Good financial conduct starts with acting early, not waiting until arrears build.
Responsible borrowing and financial difficulty support
Before you borrow, write down the amount needed, the repayment date and essential costs. Include rent, food, travel and existing credit payments in your budget. If a payday loan instalment would leave too little for these bills, consider using savings or delaying the purchase. A responsible decision starts with whether repayments fit your actual situation, not just the advertised interest rate.
Savings can avoid borrowing costs, but keep enough aside for urgent essentials such as a broken washing machine or travel to work. If you use savings, plan how to rebuild them through regular transfers after payday. Borrowing from family or friends is another possibility. Agree the amount, repayment dates and what happens if your income changes, then write down the arrangement to prevent misunderstandings.
Before accepting an offer, compare the total repayment and interest rate with your budget. Application checks assess income, spending and existing commitments. A broker can pass your application to lenders, while the lender makes its own assessment. Missed payments can affect your credit history and make future borrowing harder. Don’t submit several applications without comparing terms and understanding which checks each involves.
If repayments become difficult, contact the lender promptly and explain what has changed. Prepare a simple list of income, essential bills and debts before discussing options. MoneyHelper provides guidance on managing money and dealing with debt; its budgeting information can help you organise your figures. If a family member offers help, discuss any existing loan payments too, so support doesn’t create another strain.
If borrowing still fits your budget after considering these alternatives, review the terms and repayment amount before proceeding. You can start an application and provide accurate details about your income and outgoings.
Pixie Loans: Short Term Loans
Pixie Loans is a credit broker that connects people with independent lenders, not a direct lender. Lenders assess applications and set their own offers. For an urgent expense, consider whether a payday loan, intended for emergencies, fits your budget. Pixie Loans also matches people seeking bad credit loans or debt consolidation loans with potential lenders. Never borrow an amount that cannot be repaid on your next pay period date. Late repayment can cause you serious money problems. For help, go to moneyhelper.org.uk.
Before proceeding, review the proposed repayment amount and date alongside essential bills and existing commitments. For example, if you need to replace a broken fridge, check whether the repayments still leave enough for rent, food and travel. If borrowing would make those costs harder to manage, consider alternatives first.
For information about short-term borrowing, visit pixieloans.co.uk.
Make your next step a considered one
An unexpected expense can make borrowing feel urgent, but a short pause can help you choose with care. Before applying for cash advance loans in the UK, write down what the money needs to cover and when you expect to repay it. Then compare that repayment plan with your essential spending. If the figures leave little room for everyday costs, take time to consider another way to manage the expense.
If borrowing appears workable, read the offer carefully before agreeing. Make sure you understand the repayment schedule and what you’ll owe, then keep a note of the payment date in your calendar. A clear plan can help you stay on top of your budget and act promptly if your circumstances change.
Pixie Loans can connect applicants with independent lenders. If you’re ready to explore your options, complete the application form. Take the time you need to make a choice that fits your circumstances.
Frequently Asked Questions
Are You a Broker or Direct Lender?
Pixie Loans is a credit broker, not a direct lender. It passes applications to independent lenders, which assess them and decide whether to make an offer. Each independent Financial Service Provider may perform a credit check; Pixie Loans does not participate in that decision. Compare any offer with your budget before accepting. Late repayment can cause you serious money problems. For help, go to moneyhelper.org.uk.
How Much Can I Borrow?
The amount available depends on the lender’s assessment and terms. Before applying, work out what you need for the expense and what you can repay by your next pay period date. Never borrow an amount that cannot be repaid on your next pay period date. For help, go to moneyhelper.org.uk.
Are Bad Credit Applicants Accepted?
You can apply if you have a poor credit history, but each lender decides whether to offer credit. Pixie Loans can connect applicants seeking bad credit loans with independent lenders; it can’t promise approval or decide the outcome. Include accurate details about your income and regular commitments. For help, go to moneyhelper.org.uk.
Can I Apply over the Phone?
Pixie Loans uses an online application form, so submit your details online. Have your income and regular outgoings ready, then review the information before sending it. This helps avoid errors that could affect a lender’s assessment. If you need help understanding borrowing costs, compare the repayment amount with your budget first. For help, go to moneyhelper.org.uk.
Can I Get a Same Day Loan with Bad Credit?
A same-day loan with bad credit isn’t guaranteed. A lender decides whether to offer credit after assessing your application, and funding depends on its process and payment timing. Funds can be transferred to your bank account within the hour if the lender offers that service; otherwise, it may take the next business day or 2-3 business days, and in some cases up to 5 working days. For help, go to moneyhelper.org.uk.
I need a payday loan quickly, can you help?
Pixie Loans can connect you with independent lenders offering payday loans, but it can’t guarantee an offer or how quickly a lender will decide. Apply online and review the proposed repayment date and total due before accepting. Payday borrowing is intended for emergencies, not ongoing expenses. For help, go to moneyhelper.org.uk.