Payday Loans vs Credit Unions in the UK: How to Compare Your Options
A broken boiler or an unexpected bill can make borrowing feel urgent. But choosing between a payday loan and a credit union loan isn’t just about getting money quickly: repayments need to fit your budget too. If you’re weighing up payday loans vs credit unions uk, the right choice depends on affordability and whether you can access the borrowing, not simply its label.
It’s understandable to be unsure how these options differ, what they may cost and whether you can join a credit union. This guide explains how access and repayment terms can vary, and how to compare written offers rather than rely on promotional claims. The Bank of England reported 2.17 million adult credit union members in the UK in the first quarter of 2026, but membership figures don’t tell you whether a particular credit union will accept your application. Before borrowing, check the total repayable and each payment against your essential bills. You’ll also find practical next steps if neither option seems affordable.
Key Takeaways
- See how payday loans vs credit unions uk differ in purpose, access and repayment structure.
- Neither option is automatically better. Compare the written agreement, total repayable amount and what happens if you miss a payment.
- Use a simple decision process: identify the need, explore alternatives and test repayments against your budget.
- Pixie Loans connects applicants with independent lenders. An application does not guarantee an offer, and Pixie Loans does not provide financial advice.
Payday loans vs credit unions: what is the difference?
Payday loans vs credit unions uk: a payday loan is short-term borrowing from a lender, while a credit union is a member-owned co-operative that lends to eligible members. The application process, eligibility rules and repayment terms differ, so compare the details of each written offer.
| General feature | What varies |
|---|---|
| Payday loan: short-term borrowing | Cost, payment dates and terms |
| Credit union: member borrowing | Membership eligibility and loan terms |
How does borrowing through a credit union work?
You generally need to meet the credit union’s membership rules before applying for a loan. These rules and the loan application process differ between institutions. Read the membership and loan information carefully, and see this UK credit union overview.
What does a payday loan usually mean?
A payday loan is short-term borrowing, but the amount, repayment dates and other terms depend on the lender’s assessment. For an urgent repair, such as a broken boiler, work out whether the repayment would still leave enough for rent, food and regular bills. Explore short-term loan information only after checking affordability.
Are payday loans always worse than credit union loans?
No. The loan type alone doesn’t show which offer is more suitable. Compare the written agreements and check the total repayable, payment amounts and dates, any applicable charges, and what could happen if you miss a payment. An advertised example may differ from your personalised offer, so use the terms provided for your application.
Which costs and terms should you compare?
Compare offers for the same amount and borrowing period. Look at the total repayable as well as each instalment: a smaller payment may mean repaying for longer and paying more overall. Check whether the dates match when money comes into your account.
What if repayments may not fit your budget?
List essential bills and existing credit payments before deciding what you can afford. If a new repayment could leave too little for essentials, pause rather than borrowing to cover the shortfall. You can seek free, impartial debt guidance before applying.
How to decide between a payday loan and a credit union
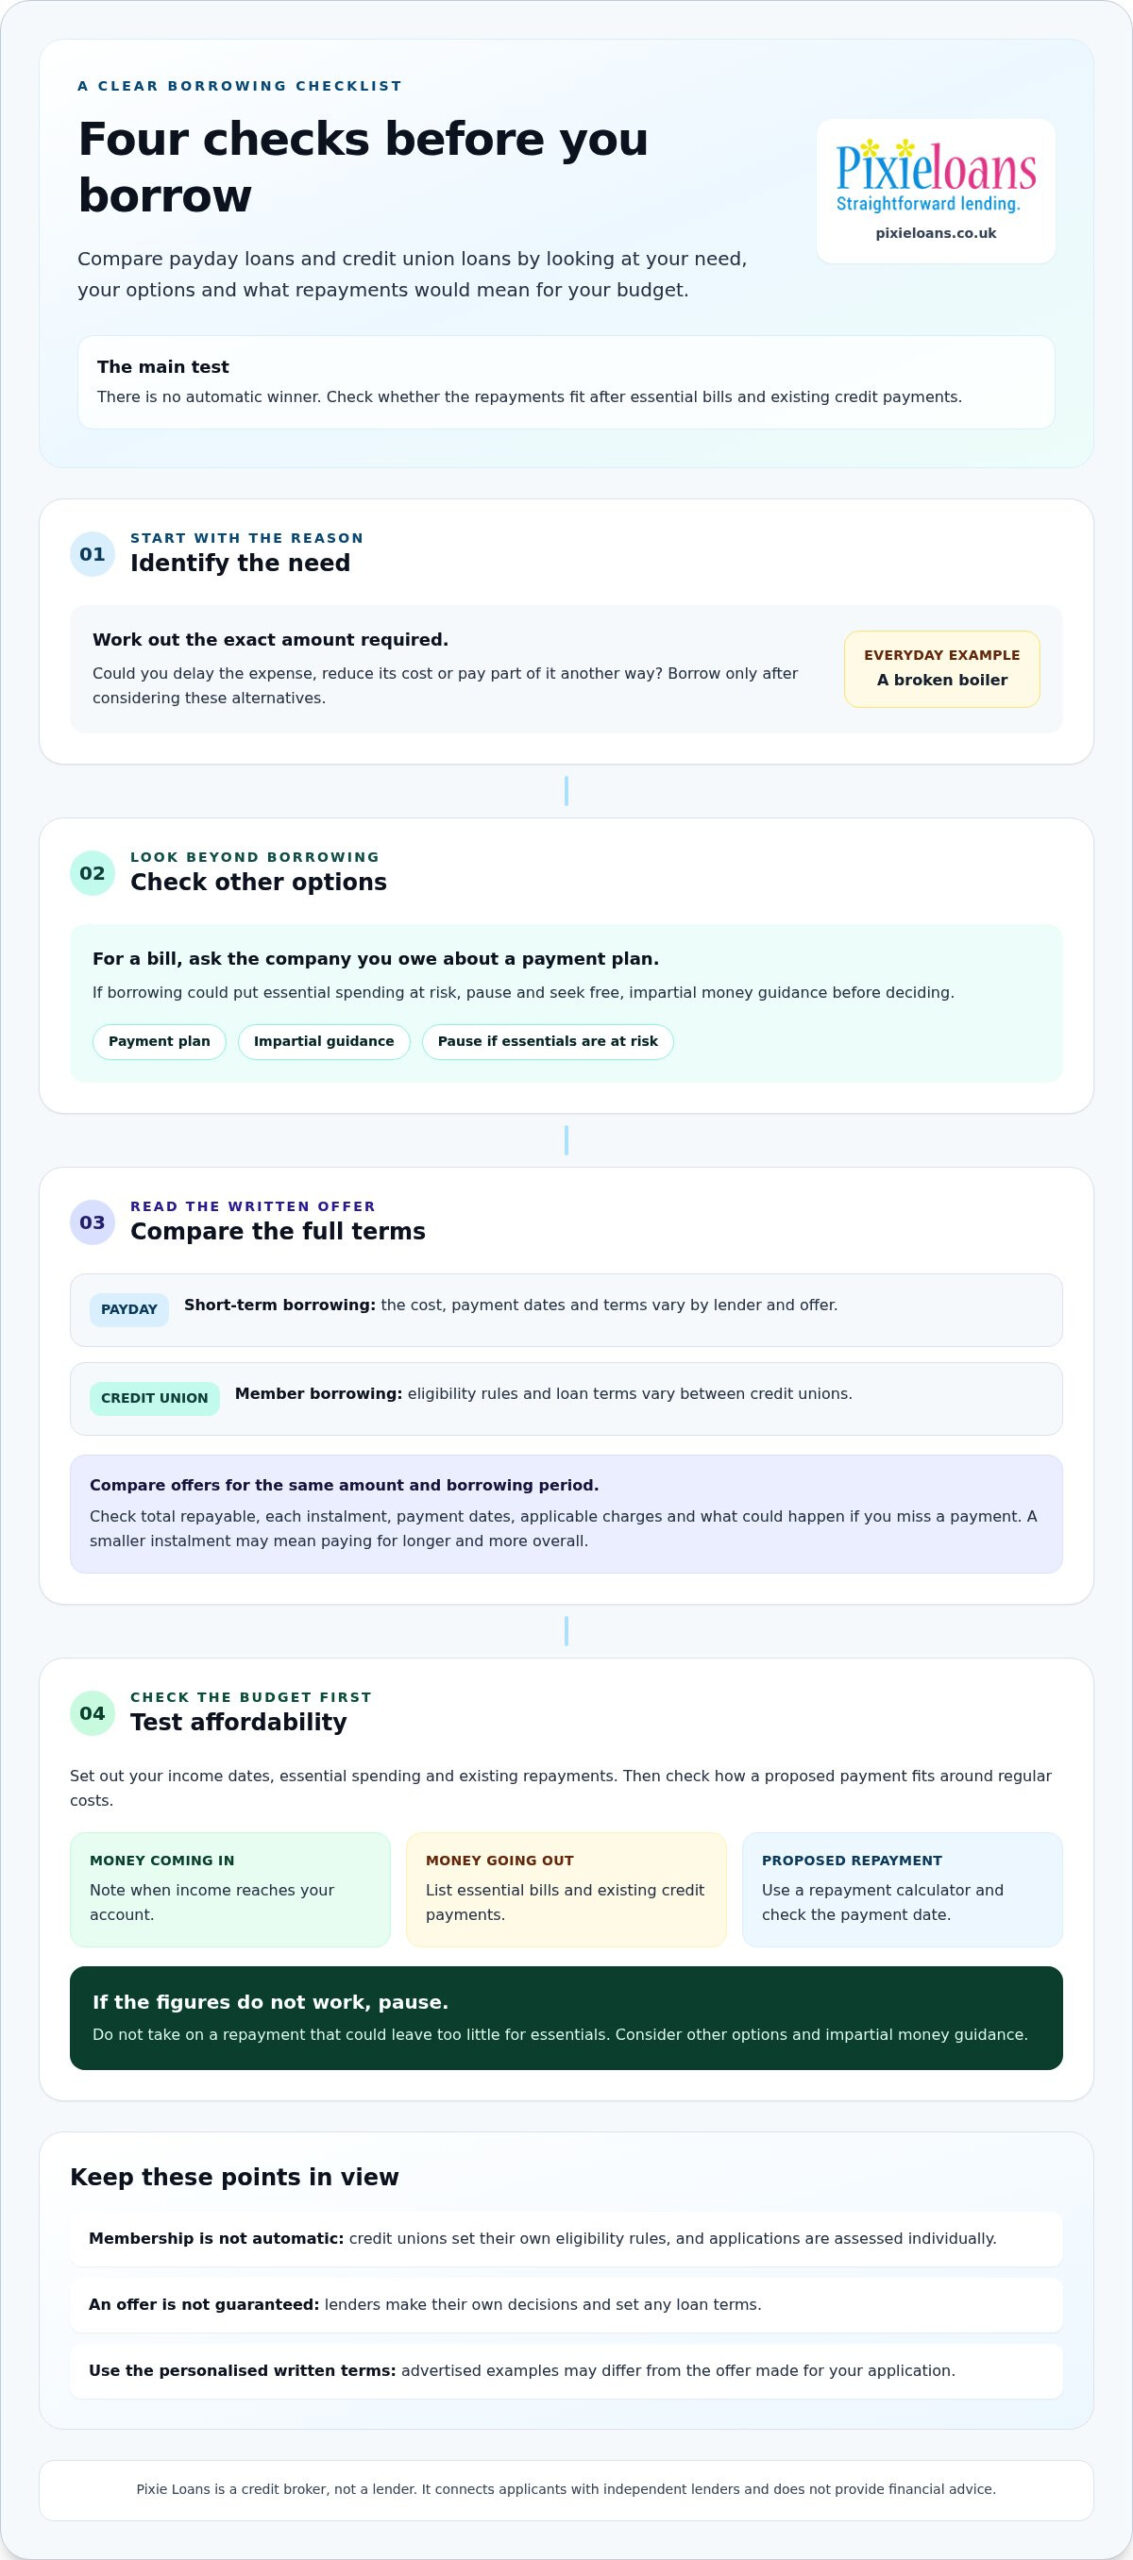
Use this four-step check before choosing. With payday loans vs credit unions uk, eligibility and repayment terms depend on the provider and your application. Write down the figures so you can compare options clearly.
- 1. Identify the need: Work out the exact amount required. Could you delay the expense, reduce its cost or pay part of it another way?
- 2. Check alternatives: For a bill, ask the company you owe whether it can agree a payment plan. If borrowing could put essential spending at risk, seek impartial money guidance.
- 3. Compare terms: Check credit union membership criteria, loan decisions, payment dates and charges. Read the full terms, not just the headline payment.
- 4. Test affordability: Set out your income dates, essential spending and existing repayments. Use a loan repayment calculator, then check that the proposed payment leaves enough for regular costs.
If borrowing still appears manageable, explore loan options. An application doesn’t guarantee an offer.
Exploring short-term loan options through Pixie Loans
After comparing payday loans vs credit unions uk and checking your budget, you can explore short-term loan information. Pixie Loans is a credit broker, not a lender. It connects applicants with independent lenders, and it does not provide financial advice.
What happens when you explore an application?
Your details may be considered by lenders, but applying doesn’t guarantee an offer. The lender makes its own decision and sets any terms. If you receive an offer, read it carefully and compare the total repayable and payment schedule with your budget before deciding.
Where can you continue comparing and planning?
Use a repayment calculator to see how potential payments fit alongside your bills and other commitments. If borrowing still looks affordable, you can explore an application.
Make a borrowing choice that fits your budget
There’s no automatic winner in the payday loans vs credit unions uk comparison. Check that the repayments fit around essential spending and existing commitments, and that you understand the total cost and payment dates. If the figures don’t work, pause and consider other options rather than taking on a repayment you may struggle to meet.
Pixie Loans is a credit broker, not a direct lender. It connects applicants with independent lenders, but an offer isn’t guaranteed and terms depend on the lender’s assessment. Pixie Loans doesn’t provide financial advice.
If you’ve checked affordability, explore an application. Take your time, read any offer in full and choose what works for your budget.
Frequently Asked Questions
Are payday loans more expensive than credit union loans?
Not necessarily, but payday loans can carry higher costs. In the UK, payday loan interest is capped at 0.8% per day, and fees and interest can’t exceed the amount borrowed. Credit union interest caps vary by UK nation. Actual costs depend on the offer and your circumstances, so compare the total repayable and payment dates in each written agreement before deciding.
Can anyone get a loan from a credit union in the UK?
No. Credit unions lend to members, and each institution sets its own membership requirements and application process. Meeting the membership rules doesn’t guarantee a loan, as the credit union assesses applications individually. Read its published membership and loan information to see whether you can apply, then check the repayment terms against your income and regular costs before committing.
Do credit unions offer payday loans?
Credit unions may offer loans to members that could meet a short-term need. These are credit union loans, not payday loans from payday lenders, and the terms depend on the individual credit union. Check the loan length, repayment schedule and total cost in the agreement. If you need money for an urgent bill, consider whether the payments will fit your budget.
How can I compare a payday loan with a credit union loan?
A payday loans vs credit unions uk comparison should focus on offers for the same amount and borrowing period. Check the total repayable, instalment amounts, payment dates, repayment frequency, applicable charges and what happens if you miss a payment. Advertised examples may not match your personalised terms. Use the written agreements and test each repayment against your income, essential spending and other credit commitments.
Is Pixie Loans a lender or a credit union?
Pixie Loans is a credit broker, not a lender or a credit union. It connects applicants with a panel of independent lenders offering short-term, payday and unsecured loan options. Applying doesn’t guarantee an offer; any decision and terms depend on the lender’s assessment. Before proceeding, check whether a proposed repayment fits your budget and read the offer carefully. Pixie Loans doesn’t provide financial advice.