How to Improve Your Chances of Loan Approval in the UK
If you’re wondering how to improve chances of loan approval, start by pausing before you apply. Check that your application details are accurate, review your credit file and work out what repayments your budget can manage.
For example, add up your rent, bills and existing repayments before deciding whether there is room for another payment. This guide explains what lenders may consider, what to prepare and what to do if you’re declined. Pixie Loans connects applicants with independent lenders, but a potential match does not guarantee approval.
Key Takeaways
- To understand how to improve chances of loan approval, focus on accurate information and affordable borrowing, not approval tricks.
- Review your credit file and use the relevant agency’s process to correct any errors.
- Before applying, set a repayment budget, gather the information you need and compare options carefully.
- Pixie Loans connects applicants with independent lenders, but a potential match is not a promise of approval.
What affects your chances of loan approval?
Each lender decides whether to approve an application, so approval is never guaranteed. To improve chances of loan approval, make sure your details are accurate and consider whether the repayments are affordable alongside your existing costs. Lenders may assess your income, outgoings and credit history.
If bills and repayments leave little spare, another payment could put pressure on your budget. Write down your regular costs and allow for everyday spending before deciding whether to apply.
Does a credit score decide whether you are approved?
No. A score is one part of a lender’s assessment, not an automatic yes or no. Your credit report includes details about accounts and repayments, while a score summarises some of that information. You can read more about what a credit score is.
How affordability and credit history shape a loan application
Affordability depends on your income and regular costs, including bills and existing repayments. Add these up to see what remains, then consider whether a new repayment would still fit your budget. Avoid treating money left over on paper as available if it is needed for everyday costs.
What should you check on your credit report?
Review your personal details, account information and repayment records. If anything looks wrong, follow the credit-reference agency’s process for correcting it. Checking your file before applying gives you time to identify errors and make sure the details in your application are consistent.
If repayments fit your budget, use the online loan application form to explore potential lender matches. A match does not guarantee approval.
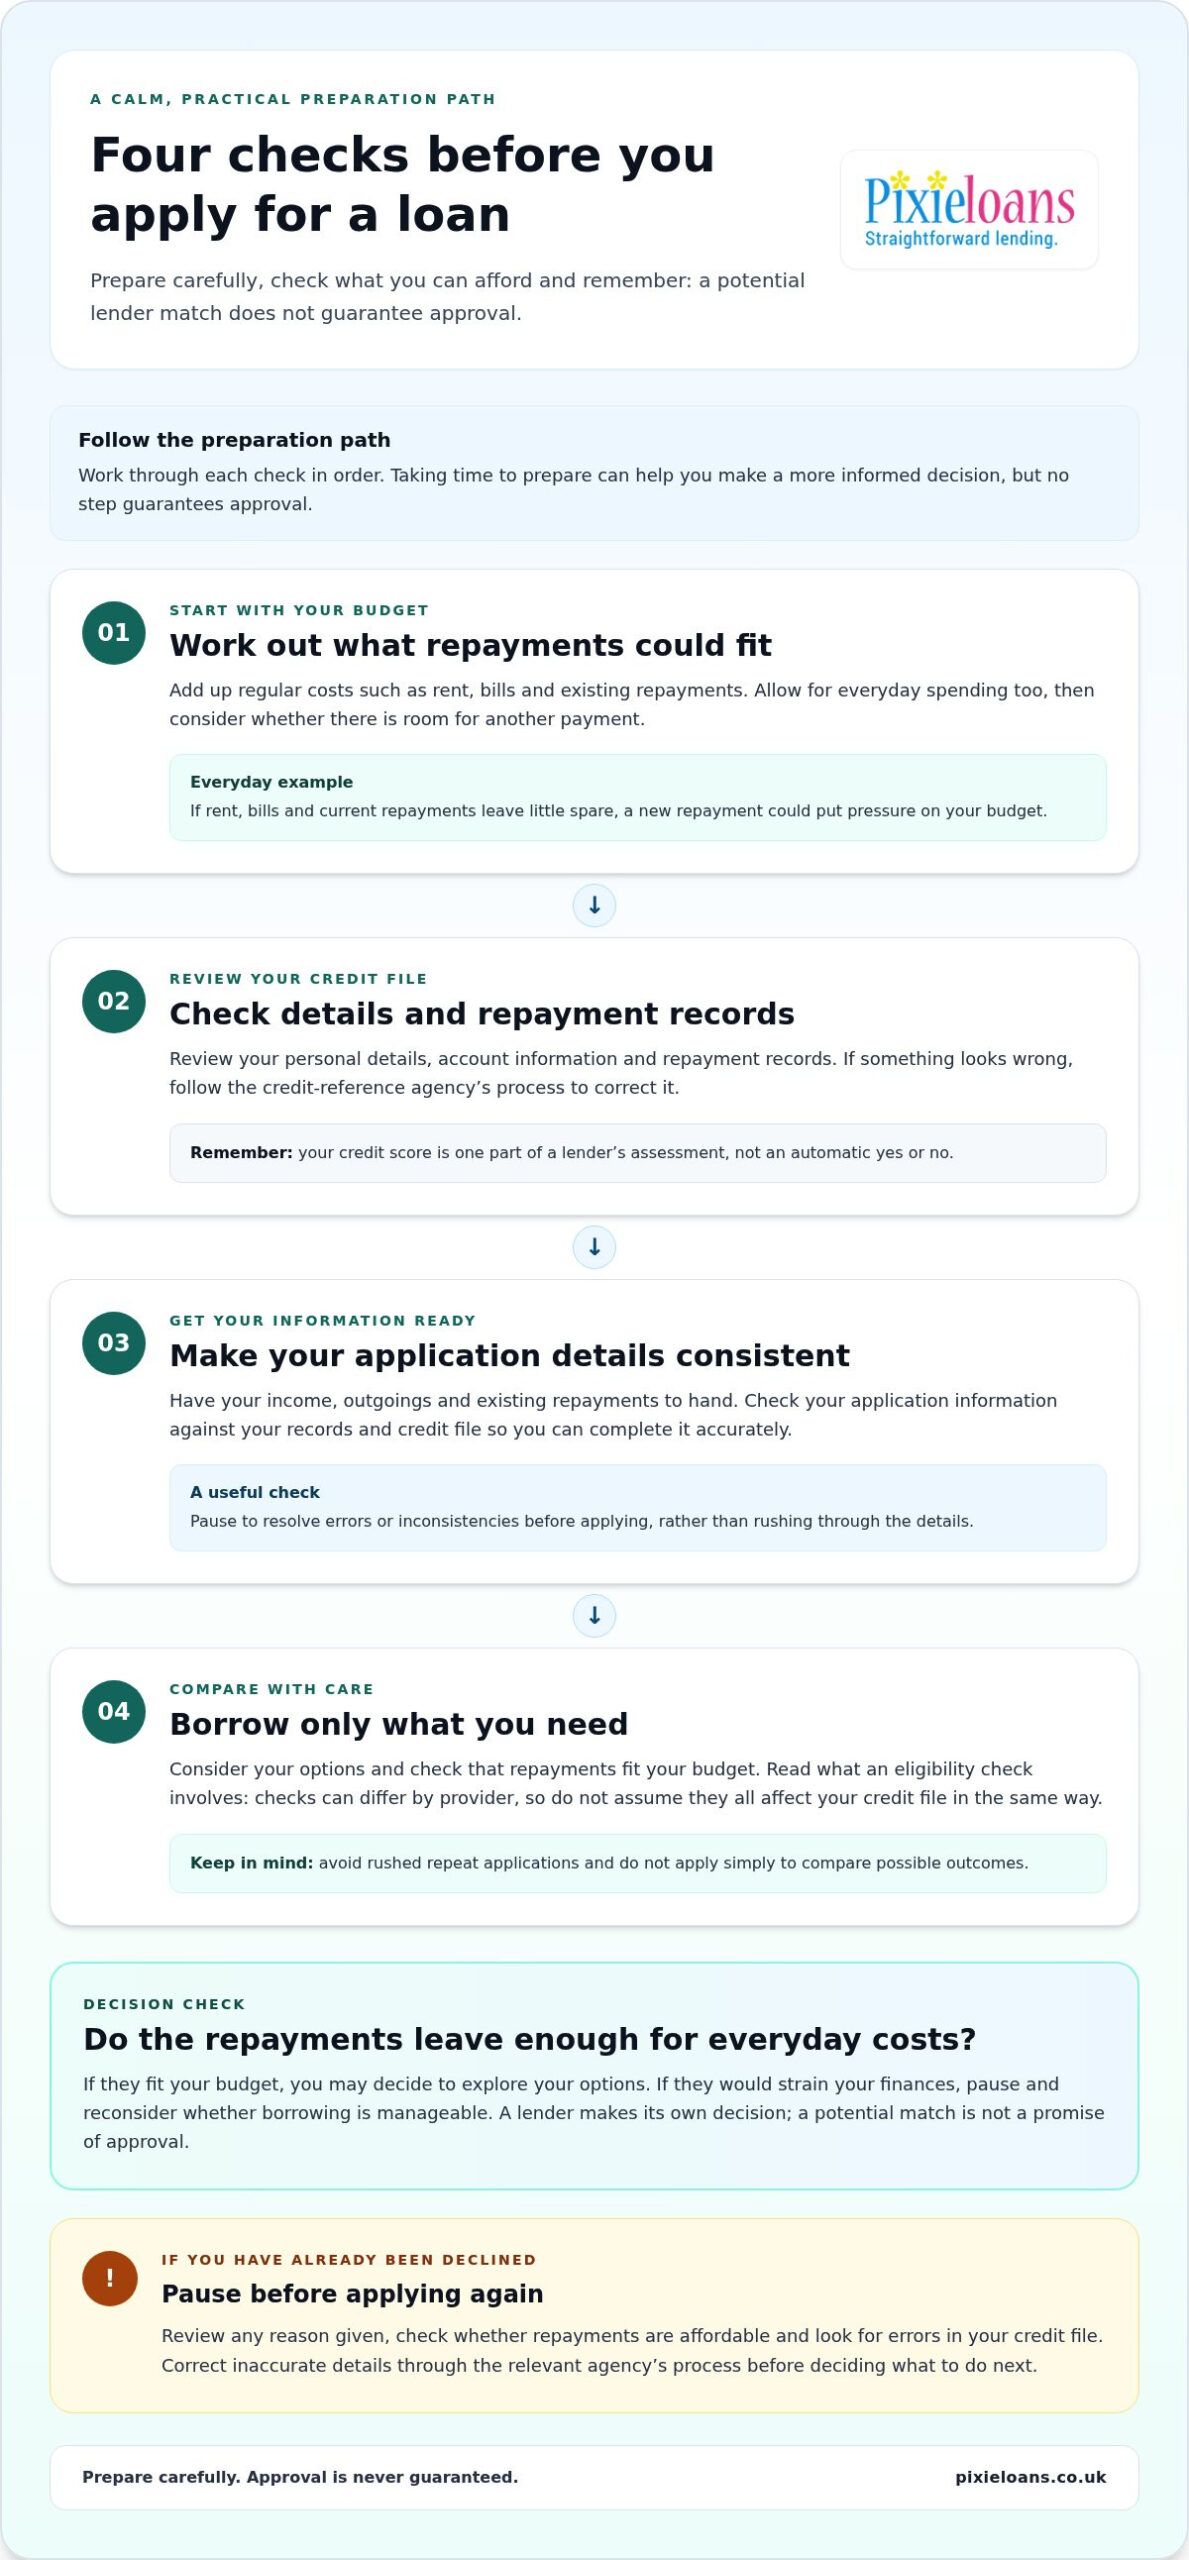
A practical checklist before you apply for a loan
- Set a budget: work out what repayment could fit after bills and other regular costs.
- Check your details: review your application information and credit file for errors or inconsistencies.
- Gather information: have your income, outgoings and existing repayments to hand so you can complete the application accurately.
- Compare options: borrow only what you need and check that the repayments fit your budget.
To understand how to improve chances of loan approval, avoid rushed repeat applications. Credit checks can differ by provider, so read what an eligibility check involves before proceeding. Do not assume every check has the same effect on your credit file.
What if you have already been declined?
Pause before applying again. Review any reason given, check affordability and look for errors on your credit file. If a short-term loan fits your need, read about short-term loans. When you are ready, you can complete an application to explore potential lender matches. This does not guarantee approval.
Choose a suitable next step, without expecting guaranteed approval
Consider applying only if you understand why you need to borrow, have checked your budget and can plan repayments. A loan repayment calculator can help you explore costs. If an unexpected bill has led you to consider borrowing, read the emergency loan eligibility guidance first and think about whether another payment would leave enough for your regular costs.
When should you consider applying?
Pixie Loans is a credit broker that connects applicants with independent lenders. Each lender makes its own decision, so a potential match is not a promise of approval. If you have reviewed your options and want to explore possible matches, you can start an application. There is no need to apply if repayments would strain your budget.
Take your next step with care
To understand how to improve chances of loan approval, focus on what you can prepare: check your details, review your credit history and make sure repayments fit your budget. No application can guarantee approval. If borrowing could put pressure on everyday costs, pause and reconsider whether it is manageable.
Pixie Loans is a UK credit broker that connects applicants with independent lenders through an online matching service for different personal borrowing needs. If you have reviewed your circumstances and want to explore potential matches, complete the loan application. Take your time and choose an option with repayments that fit your budget.
Frequently Asked Questions
Does checking my credit score improve my chances of loan approval?
No. Checking your score does not raise it or guarantee approval, but it can help you prepare. Review the information behind the score too, including your personal details and repayment records. Report errors through the relevant credit-reference agency. Understanding your credit history can help you make a more informed decision about applying and consider whether borrowing would fit your budget.
Can I get a loan if I have a poor credit history?
Possibly. Some lenders consider applications from people with poor credit histories, but their criteria differ and approval is not guaranteed. They may also consider your current circumstances and whether repayments appear affordable. Before applying, check your credit-file details and work out what you could repay after regular costs. Do not borrow more than you need or assume a bad-credit loan will suit your situation.
How many loan applications should I make?
There is no set number that suits everyone. Apply only after checking your need, budget and application details. Providers may use different checks. A full application can involve a hard credit search, which is recorded on your file, and several searches close together may concern lenders. Read what a check involves before applying, and avoid sending multiple applications just to compare possible outcomes.
What should I do if my loan application is declined?
Pause before applying again. If the lender explains why it declined your application, use that information to review your budget, application details and credit file. Correct inaccurate information through the relevant credit-reference agency’s process, then consider whether repayments would be affordable. A decline does not mean you should immediately apply elsewhere. If borrowing does not suit your finances, waiting or considering other ways to manage the expense may be safer.
Does using a credit broker guarantee loan approval?
No. A credit broker can connect you with lenders, but each lender makes its own decision and a potential match is not a promise of approval. Pixie Loans is a UK credit broker that connects applicants with independent lenders for different personal borrowing needs. Before applying, check that you need the loan and can manage the repayments. Use the broker’s application to explore possible matches, not as a guarantee of borrowing.