Poor Credit No Guarantor Loans: 2026 UK Guide
What if you no longer need a friend or family member to co-sign an agreement just to access borrowing? If you have had past credit hiccups, asking someone else to guarantee your debt feels deeply uncomfortable and stressful. Fortunately, lending criteria have evolved. Finding reliable poor credit no guarantor loans is no longer about leaning on third-party favours; it centres on proving your actual ability to repay today.
You shouldn’t have to risk personal relationships or worry about upfront fee scams when dealing with an unexpected bill. In this guide, you’ll discover how to secure an unsecured loan with poor credit without risking a guarantor’s finances. We examine how modern Open Banking assessments review your real-time budget, how soft searches protect your credit file from rejection footprints, and how to identify authorised UK credit brokers with confidence.
Key Takeaways
- Explore how poor credit no guarantor loans enable you to borrow independently without putting a loved one’s personal finances on the line.
- Learn how modern Open Banking tools assess your current disposable income and day-to-day affordability rather than judging you solely on past credit mistakes.
- Discover practical steps to evaluate borrowing costs and calculate sustainable repayments before committing to an unsecured loan agreement.
- Understand how using an authorised UK credit broker helps you check eligibility across vetted lenders with soft searches that protect your credit score.
Understanding Poor Credit No Guarantor Loans in the UK
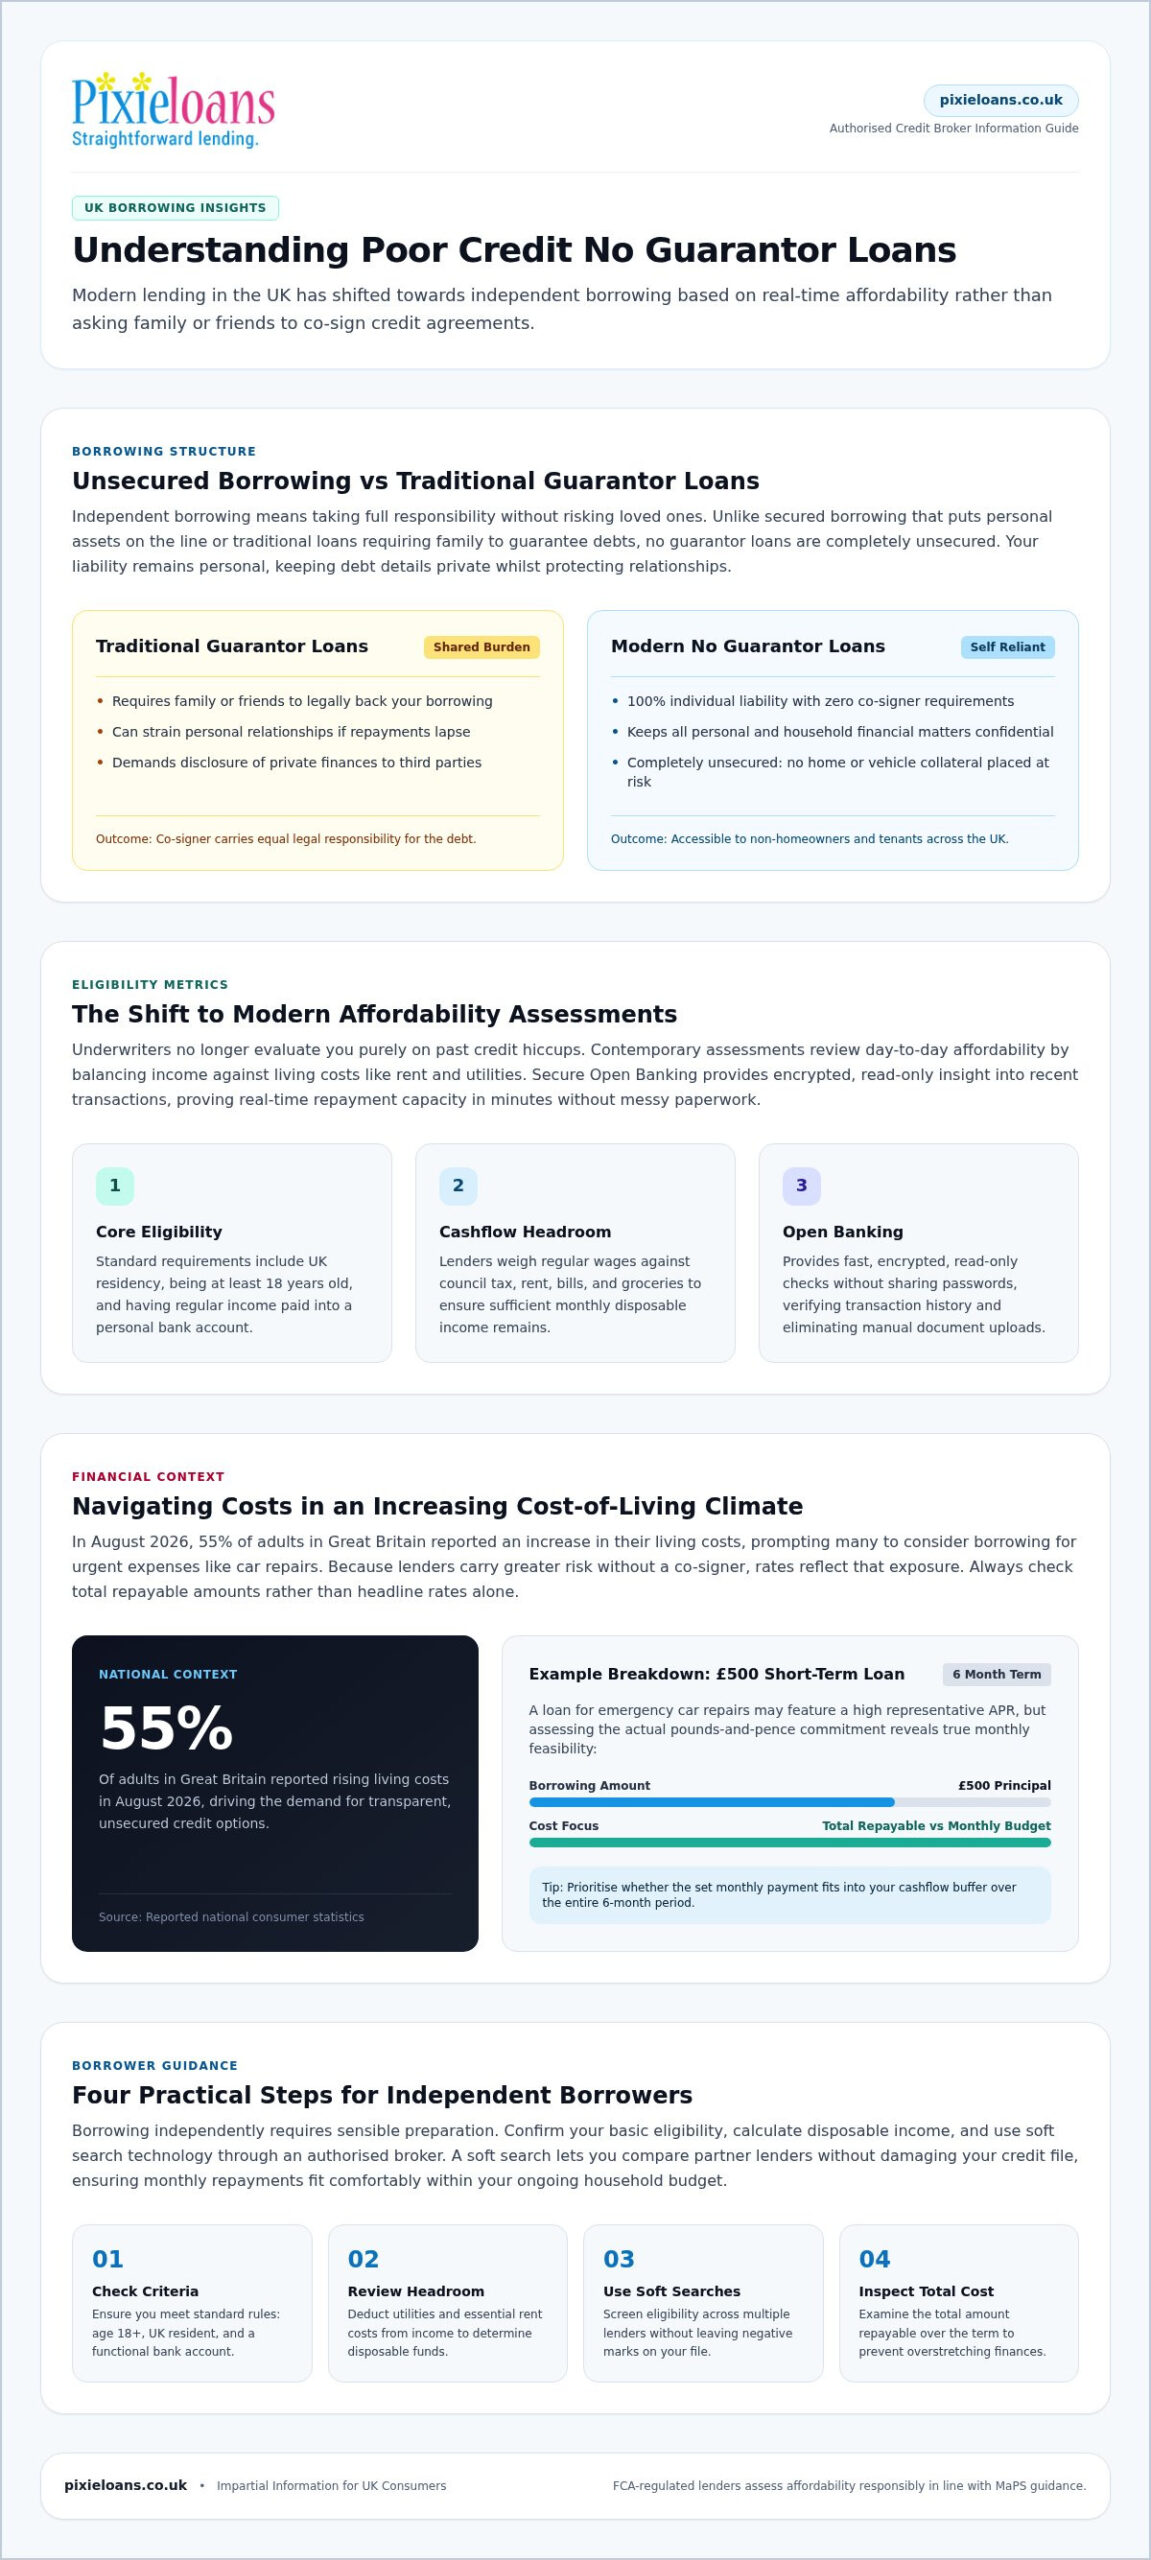
Independent borrowing means taking full responsibility for your financial decisions without relying on collateral or co-signers. Unlike secured borrowing that places your home or car at risk if life takes an unexpected turn, poor credit no guarantor loans are completely unsecured agreements. You don’t need equity to qualify, making them accessible to private tenants and non-homeowners across the UK. Every FCA-regulated lender must assess your circumstances responsibly, ensuring debt terms remain manageable. For impartial guidance on consumer rights, resources from the Money and Pensions Service (MaPS) can help you evaluate borrowing safely.
What Distinguishes a No Guarantor Loan from Traditional Borrowing?
Traditional subprime lending often demands a family co-signer to shoulder the debt if repayments lapse. In contrast, unsecured poor credit no guarantor loans keep liability solely on you. If a boiler breakdown or unexpected repair creates an urgent shortfall, exploring options like short term loans allows you to manage cashflow hiccups independently, without legally binding a relative to your agreement.
Why Borrowers Prefer Independent Credit Over Guarantor Support
Asking a loved one to back a loan is often uncomfortable and emotionally draining. Sharing sensitive personal debt details can strain close family bonds or break lifelong friendships, especially if your income changes unexpectedly later on. Handling your borrowing on your own terms provides vital peace of mind. By keeping your finances private, you retain complete independence over your monthly budget while working to rebuild your financial standing one payment at a time.
How Lenders Assess Eligibility Without a Guarantor
Qualifying for poor credit no guarantor loans no longer depends entirely on a static three-digit score. Specialist underwriters now evaluate your current financial conduct rather than penalising you indefinitely for past missed payments. Standard criteria require UK residency, being at least 18 years old, and earning regular income paid into a personal bank account. As older defaults age, their negative impact naturally fades. Seeking impartial advice on borrowing money also provides clarity on your legal protections before entering a contract.
The Shift from Credit Scores to Modern Affordability Metrics
Instead of rejecting an impaired file outright, contemporary lenders assess what you can realistically afford each month. They examine your debt-to-income ratio by balancing regular earnings against essential expenses such as rent, council tax, utilities, and groceries. A borrower who had an unsettled bill years ago but now manages reliable disposable income is viewed constructively. If clear cash headroom remains after settling everyday living costs, obtaining poor credit no guarantor loans becomes straightforward because contemporary affordability metrics carry far more weight than past bureau mistakes.
Open Banking: Secure Digital Verification Explained Simply
Open Banking simplifies this affordability evaluation securely. It gives lenders encrypted, temporary, read-only access to view recent transaction records without ever revealing your banking passwords or credentials. This completely removes the tedious chore of scanning paper payslips or utility bills, speeding up underwriting decisions to mere minutes. By providing a clear snapshot of your day-to-day spending discipline, it proves repayment capability right away. If you want to check your lender matches quickly, complete an online application form using soft searches to protect your credit score.
Evaluating Costs, Risks, and Key Borrowing Alternatives
Borrowing without a co-signer requires careful budgeting because lenders assume greater financial risk. When you take out poor credit no guarantor loans, the lack of backing assets means lenders offset their potential exposure through higher interest margins. In August 2026, 55% of adults in Great Britain reported an increase in their living costs, leading many households to turn to unsecured borrowing for urgent needs. Taking time to evaluate the full commitment protects your household budget from becoming overstretched.
Understanding Higher APRs on Independent Bad Credit Finance
Representative APRs reflect the risk profile of lending without a secondary guarantor. Instead of fixating purely on the headline rate, always inspect the total repayable amount across the full term. Borrowing £500 to repair a car over six months might show a high annual percentage rate, yet the exact pounds-and-pence interest charge could remain entirely manageable for your monthly cashflow. To check potential commitments beforehand, enter your desired borrowing figures into an online loan repayment calculator.
Responsible Alternatives to Consider Before Submitting an Application
Before applying for any commercial product, consider whether lower-cost avenues exist for your situation:
- Credit unions: Community-based cooperatives offering capped interest rates for local members.
- Salary advance schemes: Employer-backed programmes allowing early access to wages you have already earned.
- Free debt advice: Non-profit services such as StepChange, National Debtline, or MoneyHelper that help restructure unmanageable balances.
Official data published in insolvency statistics confirmed 11,644 individual insolvencies in England and Wales during August 2026 alone. If your budget is already in deficit, seek free debt advice first. If you have confirmed that an independent loan is the right short-term solution, apply online now to compare suitable lenders safely.
How to Apply Safely for a Loan Through a Credit Broker
Applying via an FCA-authorised credit broker saves time and shields your credit profile. Rather than applying to multiple direct lenders one by one, a broker uses a single digital form to scan a vetted lending panel. Legitimate UK brokers never charge upfront administration fees to arrange borrowing. If a company demands money before releasing funds, it is a scam. When seeking poor credit no guarantor loans, using an established intermediary ensures you connect only with lenders whose criteria match your personal circumstances.
The Protection of Soft Search Technology During Matching
Submitting several formal credit applications within a short window leaves hard footprints on your credit file, which makes lenders cautious. A credit broker prevents this by utilising soft search technology during initial matching. Soft searches let lenders assess whether you qualify without lowering your credit score. These initial checks remain visible only to you on your personal file, staying completely hidden from third-party credit providers. A formal hard search is carried out only when you accept a specific lender’s final agreement.
Completing Your Online Request Smoothly and Efficiently
To ensure a swift process, gather your personal details before beginning: three years of UK address history, proof of regular income, and your bank details. When you apply online today, state your typical living costs and essential household bills honestly. Clear financial reporting gives automated underwriting systems the data required to establish fair terms. If you require poor credit no guarantor loans for an unexpected emergency, digital broker matching delivers quick clarity without exposing your credit score to unnecessary rejection marks.
Take Control of Your Borrowing with Confidence
Securing credit when dealing with unexpected expenses shouldn’t mean sacrificing your privacy or straining family ties. Thanks to modern affordability assessments, accessing poor credit no guarantor loans allows you to resolve urgent cash shortfalls strictly on your own terms. Today’s lenders look closely at your current monthly budget and regular disposable income, so past credit blips won’t automatically prevent you from securing independent, unsecured borrowing.
Partnering with a reputable credit broker makes discovering suitable options straightforward and stress-free. You gain immediate access to a vetted panel of established FCA-authorised UK lenders, soft search eligibility checks that keep your credit file protected, and zero upfront broker fees. Take a positive step toward managing your finances without leaning on relatives. Check your loan options today and find a borrowing solution built around your real affordability.
Frequently Asked Questions
Can I get a loan with very poor credit and no guarantor?
Yes, you can secure poor credit no guarantor loans even with severe credit impairments. Specialist lenders prioritise your current disposable income and day-to-day spending patterns over historical defaults. If you can clearly demonstrate steady earnings and adequate financial headroom to cover the monthly instalments comfortably, many independent UK lenders will consider your application favourably.
Will applying for a no guarantor loan harm my credit score?
Checking your initial options won’t hurt your credit score when you use a credit broker. Brokers conduct soft credit checks to match you across suitable lenders, which remain visible only to you on your record. A full, hard search is recorded only if you formally accept a lender’s loan offer and proceed with the contract.
How quickly can funds be released after loan approval?
Funds can often be sent to your bank account within minutes once your application receives final approval. Most contemporary direct lenders utilise automated verification and the UK Faster Payments system to process transactions swiftly. The exact timing depends on your individual bank’s processing speeds and whether additional identity documents are required.
Do I need to own my home to qualify for unsecured loans?
No, homeownership isn’t required to qualify for poor credit no guarantor loans. These agreements are entirely unsecured, meaning your eligibility depends strictly on your personal income and affordability rather than property equity. Private tenants, council tenants, and individuals living with family are fully eligible to apply independently.
What happens if I struggle to make my scheduled repayments?
Contact your lender immediately if you anticipate difficulty meeting an upcoming repayment instalment. Regulated UK lenders are legally obligated to treat borrowers sympathetically and can often establish temporary payment freezes or adjusted plans. You can also contact free debt advice charities like StepChange or National Debtline for confidential, practical guidance.