Easy Acceptance Loans: A Guide to Quick Decisions
Could a simple loan application still lead to a decline? “Easy acceptance loans” can sound reassuring if you’re unsure whether you meet a lender’s criteria. But it’s a marketing phrase, not a promise of approval.
Before applying, work out what you need to borrow and whether the repayments fit your budget. List your income, regular bills and existing borrowing. If a repayment would leave you short for everyday costs, pause and reconsider.
This guide explains what lenders may consider and how Pixie Loans, a credit broker, connects applicants with potential lenders. For a recent overview of loan rates, read MoneySavingExpert’s October 2026 guide.
Key Takeaways
- “Easy acceptance loans” is a marketing phrase, not a loan type with guaranteed approval. Focus on whether the borrowing suits your circumstances.
- Lenders may assess your income, regular outgoings, existing commitments and credit history. Their criteria can differ.
- Before applying, decide how much you need and compare the repayments with your household budget, including costs such as an unexpected boiler repair.
- A broker can connect you with potential lenders, but the lender makes the decision. Read on to see how the process works.
What does “easy acceptance loans” really mean in the UK?
“Easy acceptance” is a marketing phrase, not a recognised loan category or a promise of approval. A simple application does not guarantee an offer. Easy application steps describe the process, not the lender’s decision. The phrase may be associated with subprime lending, but the terms do not mean the same thing.
If you’re considering a short-term loan, check the repayment amount, schedule and total amount repayable before deciding.
Does easy acceptance mean guaranteed approval?
No. Lenders assess applications using their own criteria, so an application may be declined even if the process seems straightforward. Even in private finance where asset-based lenders such as Level 4 Funding prioritise property equity over traditional credit metrics, comprehensive underwriting is still required before an offer is made.
Why can straightforward applications still be declined?
A lender may decide that an application does not meet its requirements. For example, rent, household bills and existing repayments may leave too little income for another repayment.
What may lenders consider when assessing a loan application?
Lenders may consider your income, outgoings, existing commitments and credit history, but their approaches differ. The same details can be assessed differently by different lenders, so no single factor predicts a decision. Make sure the information you provide reflects your current finances.
Can a poor credit history affect acceptance?
It may influence a lender’s assessment, but it does not determine every decision. Read about loans for bad credit, and check your credit report for errors before applying.
Why do income and existing commitments matter?
Your regular costs affect how much money remains after bills and repayments. Add up your take-home income, essential spending and current credit commitments to see what room, if any, is left for another repayment. While personal lending scrutinises household cash flow, specialised borrowing models evaluate income differently; for example, qualification for a DSCR loan for rental property focuses on whether the asset’s rental revenue covers debt obligations rather than personal earnings.
How can you prepare before applying for an easy acceptance loan?
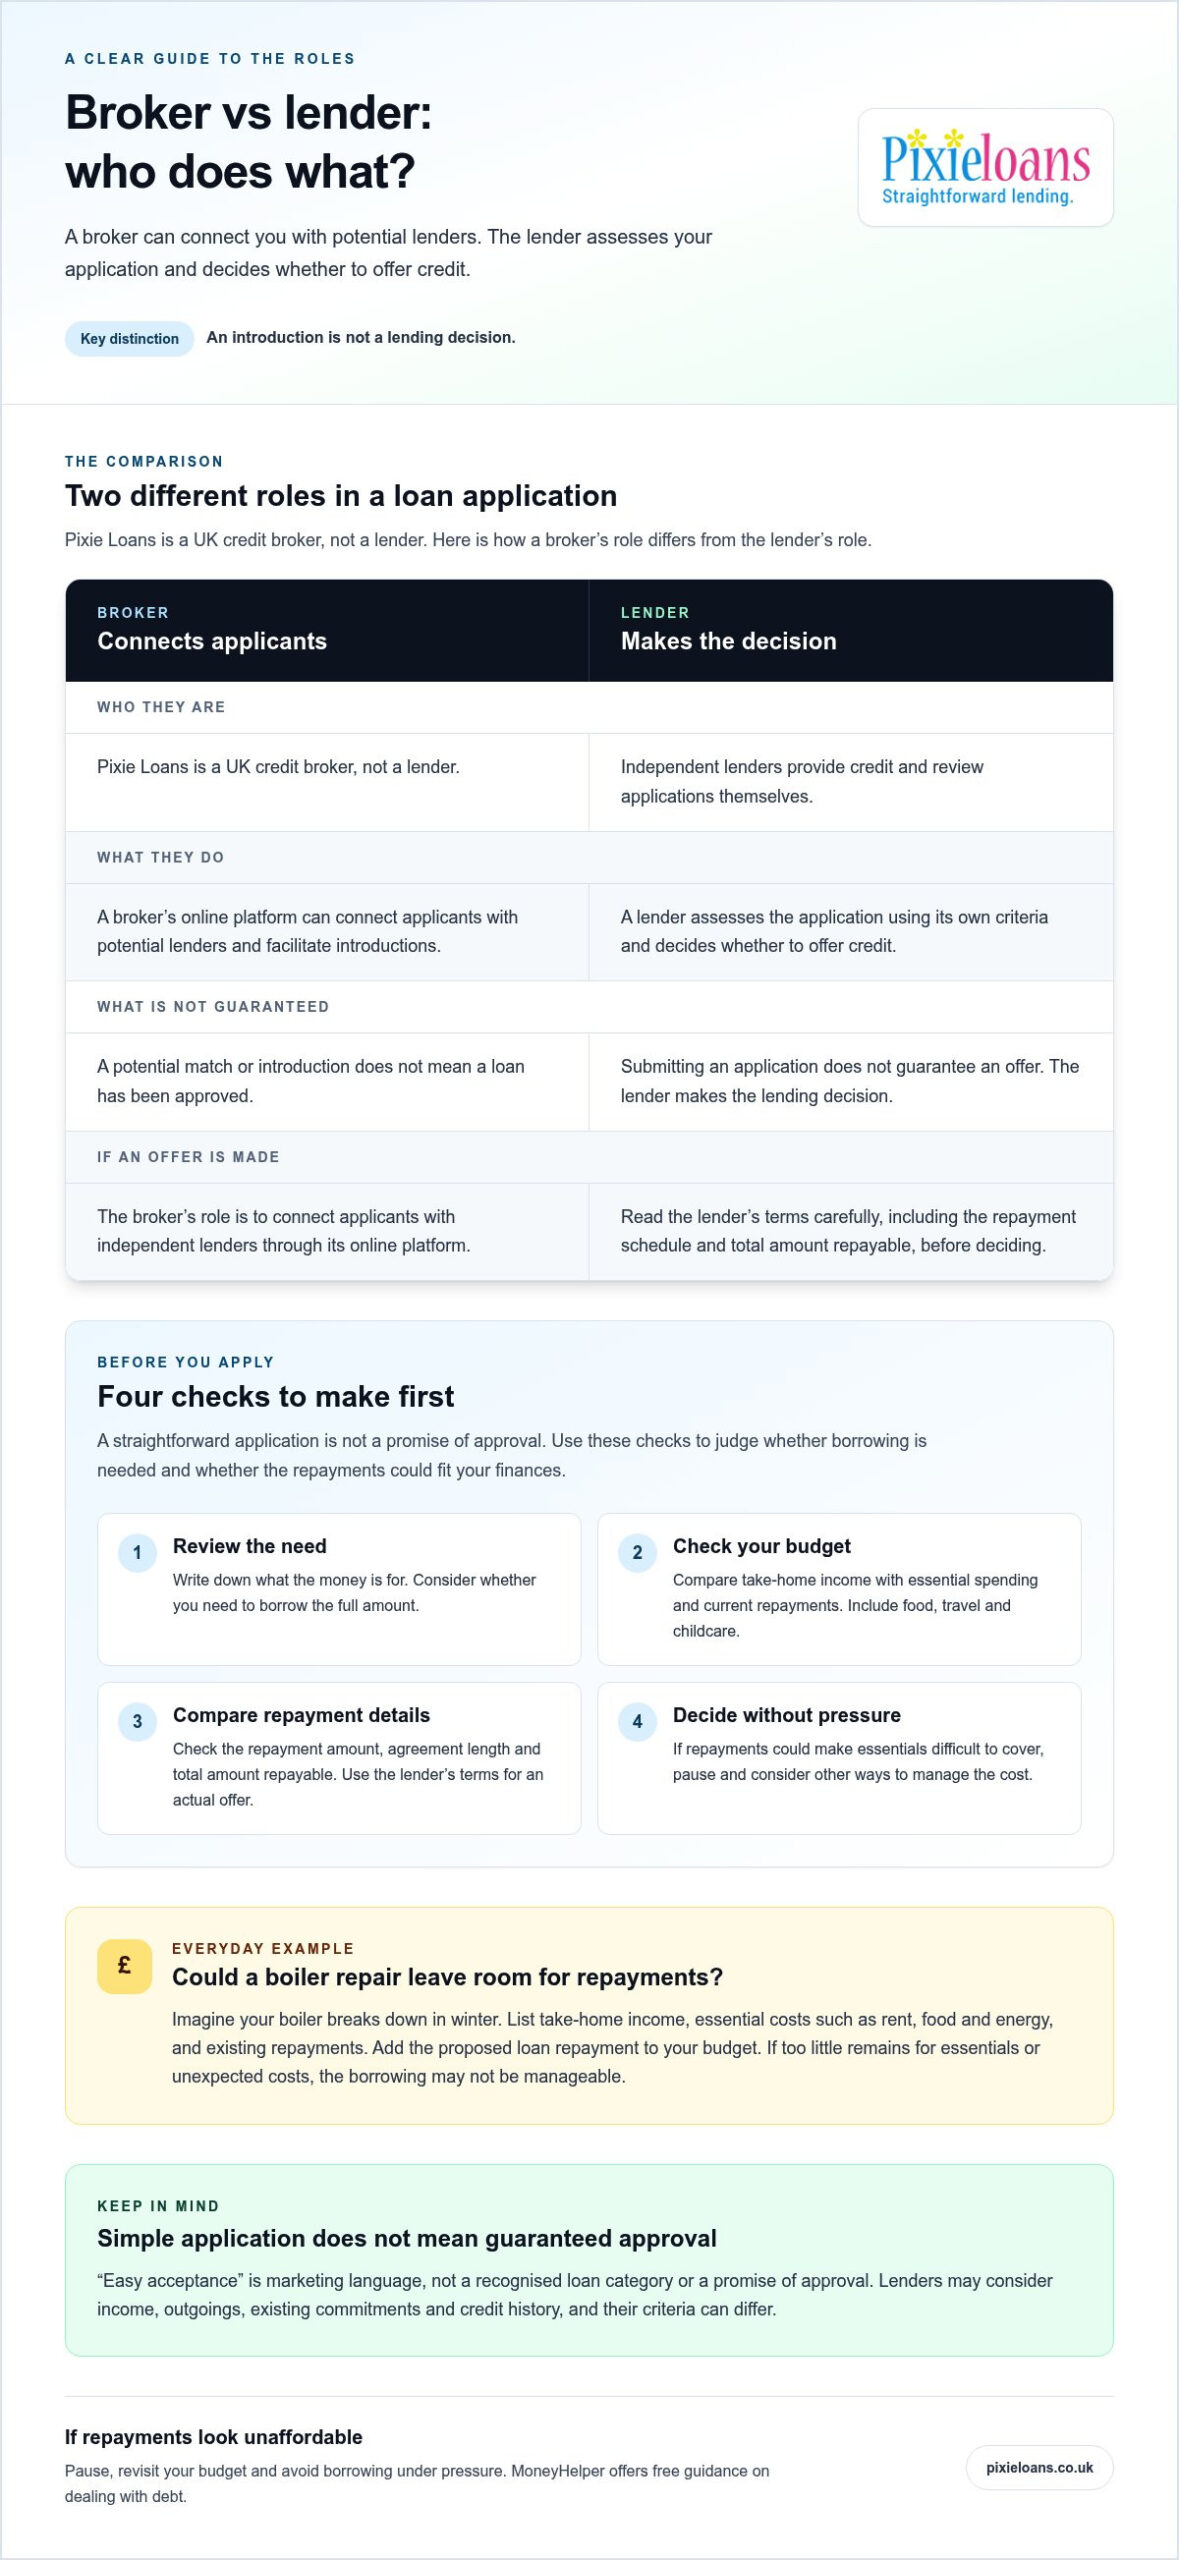
Prepare before you apply so you can judge whether borrowing is necessary and whether repayments could fit your finances. Work through these steps in order:
- Review the need. Write down what the money is for and whether you need to borrow the full amount.
- Check your budget. Compare take-home income with essential spending and existing repayments. Include regular costs such as travel, childcare and food.
- Compare repayment information. Check the repayment amount, agreement length and total amount repayable. A calculator can help you explore figures, but use the lender’s terms to understand an actual offer.
- Decide carefully. If repayments would make it difficult to cover essentials, pause and consider other ways to manage the cost.
How can you check whether repayments are affordable?
Imagine your boiler breaks down in winter. Before borrowing for a repair, list your monthly take-home income, essential costs such as rent, food and energy, and existing repayments. Then add the proposed loan repayment to your budget. If there is too little left for essentials or unexpected costs, the borrowing may not be manageable. Only consider it if the repayments appear affordable within your budget.
What should you review before submitting details?
Check that your application details are accurate and complete. Read the lender’s terms, including the repayment schedule and total amount repayable. Find out whether an eligibility check or full application search will be made and whether it may affect your credit file, as search types can differ. You can start an online loan application when you’re ready to explore a potential lender match.
What happens when you apply through a loan broker?
Pixie Loans is a UK credit broker, not a lender. Its online platform connects applicants with independent lenders, including for short-term loans. A broker can facilitate a potential match, but it cannot approve a loan or promise an offer. The lender reviews the application and decides whether to offer credit, based on its own criteria. An introduction is not a lending decision.
What is the difference between a broker and a lender?
A broker helps applicants explore potential lender matches and facilitates introductions. The lender assesses the application and decides whether to offer credit and on what terms. If you receive an offer, read the lender’s terms carefully before deciding. Pixie Loans’ role is to connect applicants with independent lenders through its online platform.
What should you do if borrowing does not look affordable?
Pause before applying. Recheck your budget, including household bills, existing repayments and costs that can vary, such as food or energy. If there is little room for another repayment, avoid borrowing under pressure. Consider whether the expense can wait or whether there is another way to manage it. If bills or debts are becoming difficult to manage, seek impartial money guidance. MoneyHelper offers free guidance on dealing with debt.
Submitting an application does not guarantee a lender will make an offer. Review any terms carefully before deciding whether to proceed.
Make your next borrowing decision with care
Give yourself time to decide whether borrowing is the right response to your situation. A loan should meet a clear need without making everyday costs harder to manage. If your budget is uncertain, revisit your figures rather than applying under pressure. Choosing not to borrow, or waiting until you have a clearer plan, can be a sensible decision too.
When considering easy acceptance loans, focus on the terms and your ability to repay, not just how simple the application appears. An application lets you explore a possible option; it does not promise an offer. Take time to read the information provided and decide whether the borrowing works for you.
Frequently Asked Questions
Are easy acceptance loans guaranteed in the UK?
No. “Easy acceptance” does not guarantee that a lender will approve an application or make an offer. Treat it as advertising language, not certainty. Check the repayment terms before applying, and avoid making plans that depend on receiving the money, such as committing to a purchase before an offer is confirmed.
Can I get a loan with poor credit?
It may be possible, but a poor credit history can affect which options a lender considers and the terms offered. Each lender has its own approach, so do not assume you will qualify or that borrowing will be affordable. Check your credit report for errors and consider whether repayments would fit alongside your existing commitments.
Does applying for a loan affect my credit score?
It depends on the type of search used. An eligibility check may use a soft search, which usually is not visible to other lenders, while a full application may involve a hard search recorded on your credit file. Practices can vary, so check what search will be made and when before submitting your details. Credit scores can also differ between credit reference agencies.
What information might I need for a loan application?
You may be asked for details to confirm your identity and help assess your finances, such as your address, employment, income and regular spending. Have accurate information to hand and make sure it reflects your current situation. Include regular commitments such as childcare or transport costs, not just rent and household bills. Requirements differ between lenders.
What should I do if I am turned down for a loan?
Pause before applying elsewhere. Review your budget and check your credit report for mistakes, such as a missed-payment record that may be inaccurate. Avoid making several applications in quick succession without understanding their likely impact on your credit file. If bills or debt are becoming difficult to manage, seek free, impartial guidance from MoneyHelper before taking on more borrowing.
If you’ve reviewed your budget and want to explore a potential lender match, start an application with Pixie Loans. A lender makes the decision, so review any offer and its terms carefully before proceeding.